Stryker plans $400m CMR Surgical investment with US sales rights
The alliance gives Stryker exclusive US sales rights for CMR Surgical’s Versius portfolio and an option to acquire the British robotics company outright.
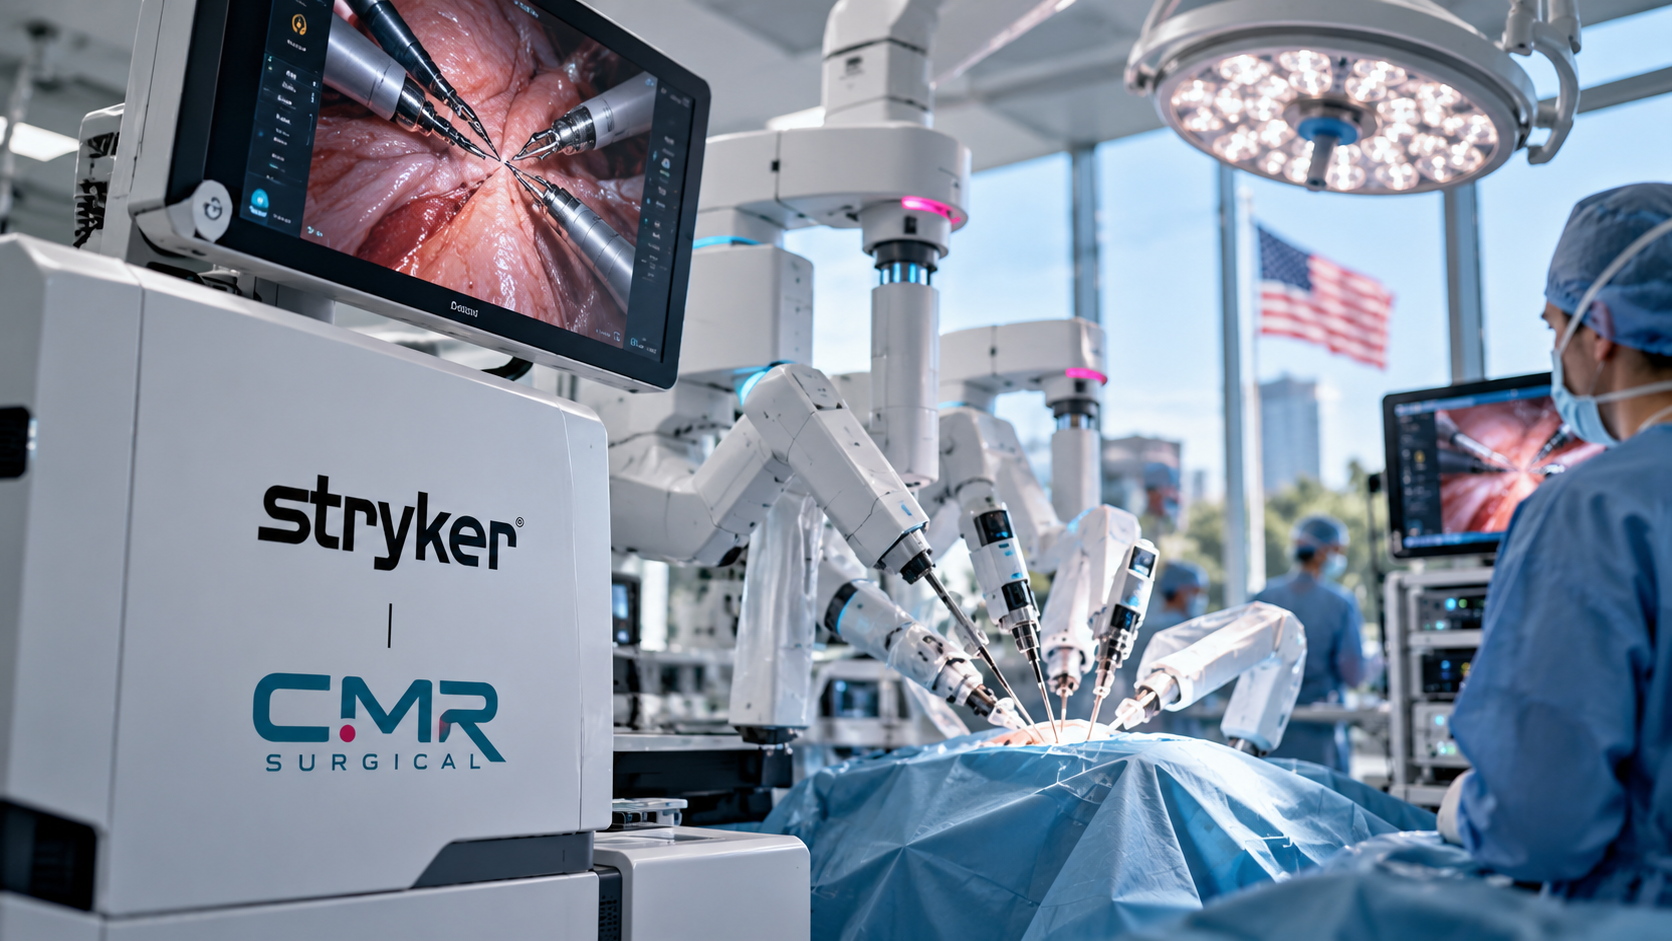
US medical technology group Stryker plans to invest approximately $400 million (£300 million) in Britain’s CMR Surgical under an alliance that combines financing, exclusive US sales rights and a potential route to full ownership. Announced on October 12, the agreement puts Stryker in charge of US sales for CMR’s Versius surgical robotics portfolio.
The preferred equity investment will support further innovation and global commercialisation of Versius. It also grants Stryker an exclusive option to acquire CMR outright in the future, subject to the agreement’s terms. The transaction remains subject to regulatory approvals and customary closing conditions; it is not a completed takeover.
For Cambridge-headquartered CMR, the strategic significance extends beyond the capital. The arrangement links its soft-tissue surgical robotics technology to an established US medtech company’s customer relationships and commercial reach, while leaving CMR responsible for portfolio development and commercialisation outside the United States.
A US sales partner, not just an investor
Stryker will serve as the exclusive US sales agent for the Versius portfolio. That makes the alliance a defined commercial expansion strategy rather than simply a funding round: CMR’s US sales effort will run through its new strategic investor, while its business elsewhere remains under its own commercial leadership.
“Stryker’s investment will give us additional strength to accelerate innovation and the continued global expansion of the Versius portfolio, while its scale and deep customer relationships create a significant growth opportunity in the United States,” CMR chief executive Massimiliano Colella said in the companies’ announcement.
Andy Pierce, Stryker’s group president for Medsurg and Neurotechnology, will also join CMR’s board. The appointment adds a governance link alongside the investment and sales agreement, bringing a senior executive from the US partner into the British company’s oversight.
Competing on operating-room flexibility
Founded in 2014, CMR is a privately held medical devices company backed by an international shareholder base. Its focus is robotic minimal-access surgery. The companies describe its second-generation robot as having established clinical experience globally and supporting a broad range of soft-tissue procedures.
The commercial pitch centres on the platform’s modular architecture. According to the announcement, that design supports flexibility across procedures, surgeon access and sites of care, allowing healthcare providers to expand robotic adoption within existing operating-room workflows. Those are the operational attributes the partners intend to use to support wider adoption.
Stryker identified hospitals and ambulatory surgery centres as target settings. The companies say demand for robotic-assisted surgery is growing, but the announcement does not quantify the US market opportunity or provide sales targets. Their stated proposition is a scalable system that preserves operational flexibility and supports the economics of a robotics programme over time.
For Stryker, the agreement provides an entry into soft-tissue robotics adjacent to its existing businesses. “Soft-tissue robotics is a high-growth adjacency and a natural extension of Stryker’s strengths in endoscopy, visualization and enabling technologies,” Pierce said. He added that the company had evaluated the segment carefully for years.
A potential acquisition, with terms still undisclosed
The acquisition option gives Stryker a path from strategic investor and exclusive US sales agent to owner. The supplied announcement does not disclose an exercise price, an option deadline or the ownership percentage that the initial investment would purchase.
The immediate strategy is clearer than the eventual ownership outcome: CMR is pairing its robotics portfolio with Stryker’s commercial reach to pursue US growth. Whether that relationship ultimately becomes a full acquisition remains a separate decision under the agreement.